The right loan, explained plainly.
Independent mortgage brokers comparing 40+ lenders to find your best rate — no bank sales pitch.
Soft credit check — your score is untouched About 10 minutes
How it works
Three steps. No pressure, no jargon.
A mortgage is the biggest contract most people ever sign. Ours is the same process either way — the only difference is we do the explaining before you commit.
Pre-qualify in about 10 minutes
Tell us the basics — price range, credit range, ZIP. We run a soft credit check, which does not affect your credit score. You get a real estimate, not a scripted phone call.
Compare offers side by side
We shop 40+ wholesale lenders and lay out the top options in plain English — rate, APR, points, and what each actually costs you at closing. No fine-print games.
Close with a person, not a portal
You pick the loan. We handle appraisal ordering, underwriting follow-ups, and title coordination through closing day — most of our purchases close in 28 days.
Today's rates
What we're actually seeing from lenders
Not national averages scraped from a headline — these are the rate sheets our brokers work from, updated every business day.
As of September 12, 2026 · updated daily
| Loan program | Rate | APR | 30-day trend |
|---|---|---|---|
| 30-Year Fixed Conforming · most popular | 6.24% | 6.31% APR | ▼ 0.09 pts |
| 15-Year Fixed Conforming · build equity faster | 5.52% | 5.63% APR | ▼ 0.06 pts |
| 5/1 ARM Fixed 5 years, then annual adjust | 5.87% | 5.94% APR | ▲ 0.04 pts |
| 30-Year Jumbo Loans above conforming limits | 6.39% | 6.44% APR | ▼ 0.05 pts |
Pricing assumes 740+ credit, 20% down, a $417,000 conforming loan, owner-occupied primary residence, and no lender credits. Rates change daily and your rate depends on your full picture — check yours in about 10 minutes. APR includes estimated fees and will be higher than the note rate.
Pre-qualification
See what you'd actually qualify for.
Four questions, then a few basics. We run a soft credit check and come back with a genuine estimate of your rate and budget — the same numbers we would show our own families.
- Your credit score is untouched. Soft inquiry only — no hard pull until you formally apply for a loan you choose.
- A real broker reads it. Dana, Marcus, or Priya reviews your file personally — no call-center dialers, no rate-chasing spam.
- Answers within one business day — usually the same afternoon if you submit before 2pm Pacific.
Prefer to talk first? Call (503) 555-0148 — a licensed broker answers, Monday through Saturday.
Check my rate
Takes about 10 minutes. Required fields are marked with .
Request received
A licensed broker will review your details and reach out within one business day.
Something went wrong sending your request. Please try again, or call us at (503) 555-0148.
Our brokers
Licensed people, accountable by name.
Every NMLS number below is verifiable at nmlsconsumeraccess.org. When you work with Cornerstone, you work with one of these three — start to close.
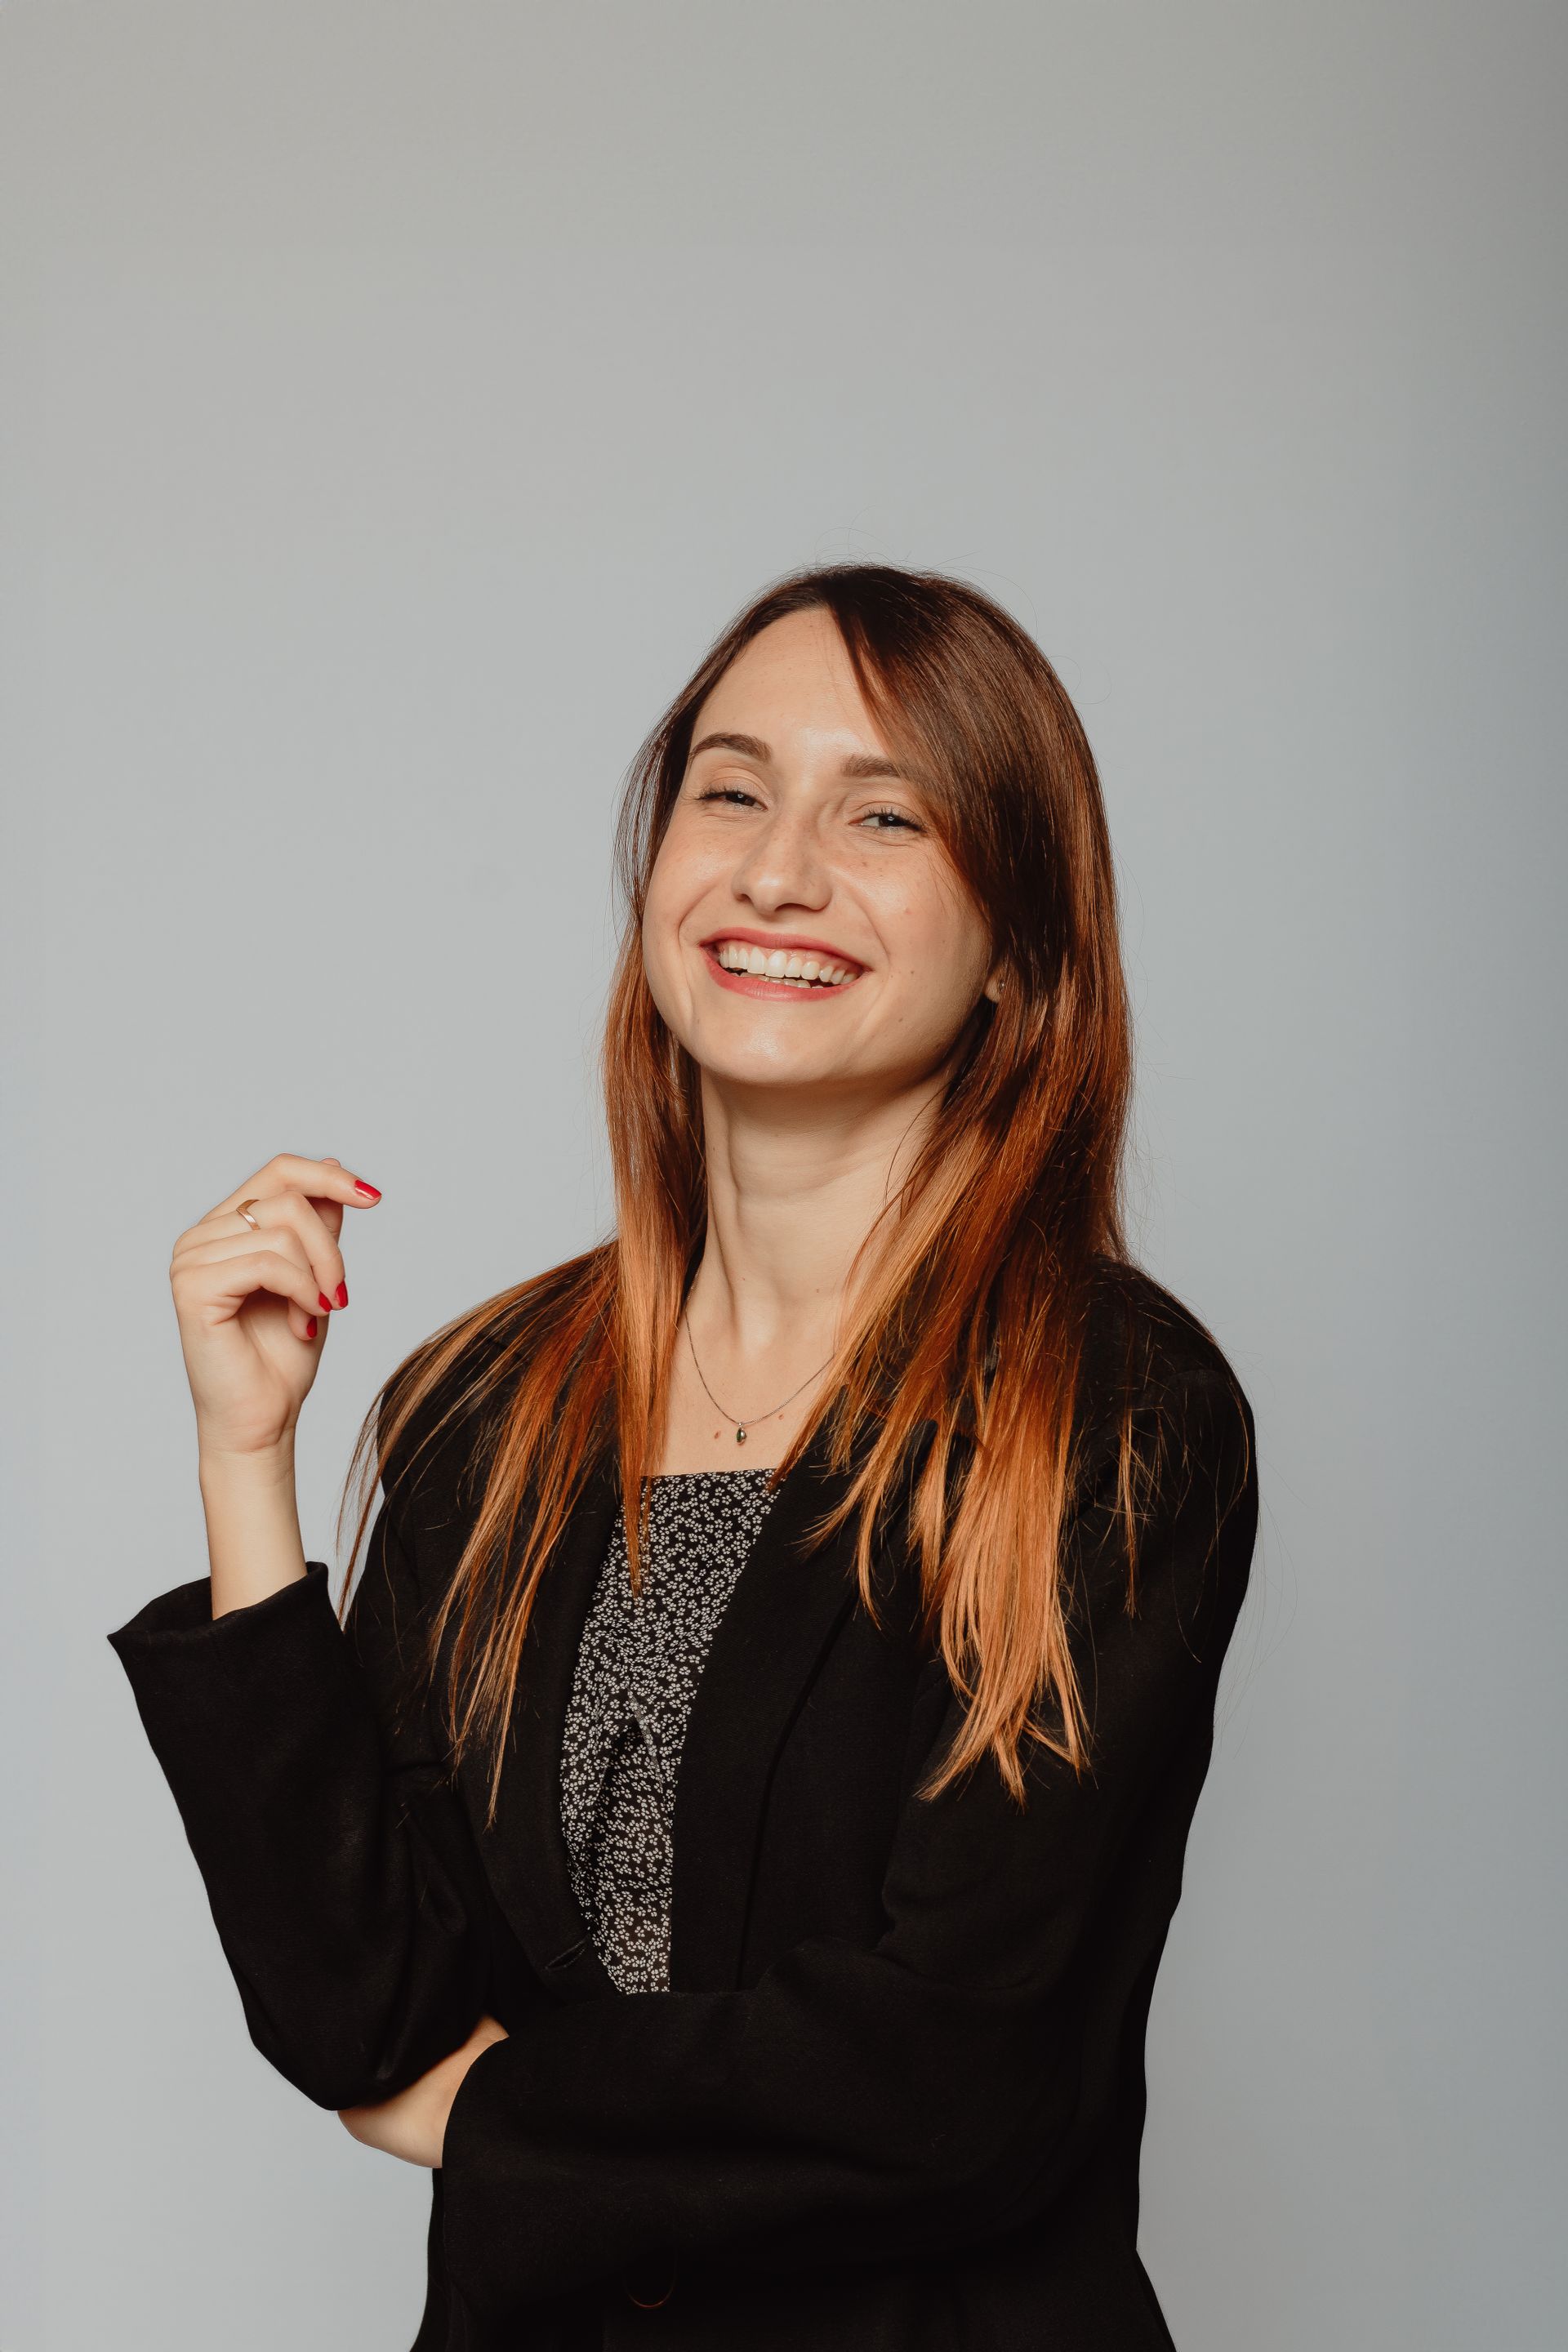
Dana Whitfield
Founding Broker
Dana spent nine years as a credit union underwriter before founding Cornerstone in 2016 — she reads loan files the way lenders do, and negotiates accordingly. Specializes in complex self-employed income.
NMLS #1487236 · 19 years in mortgage lending
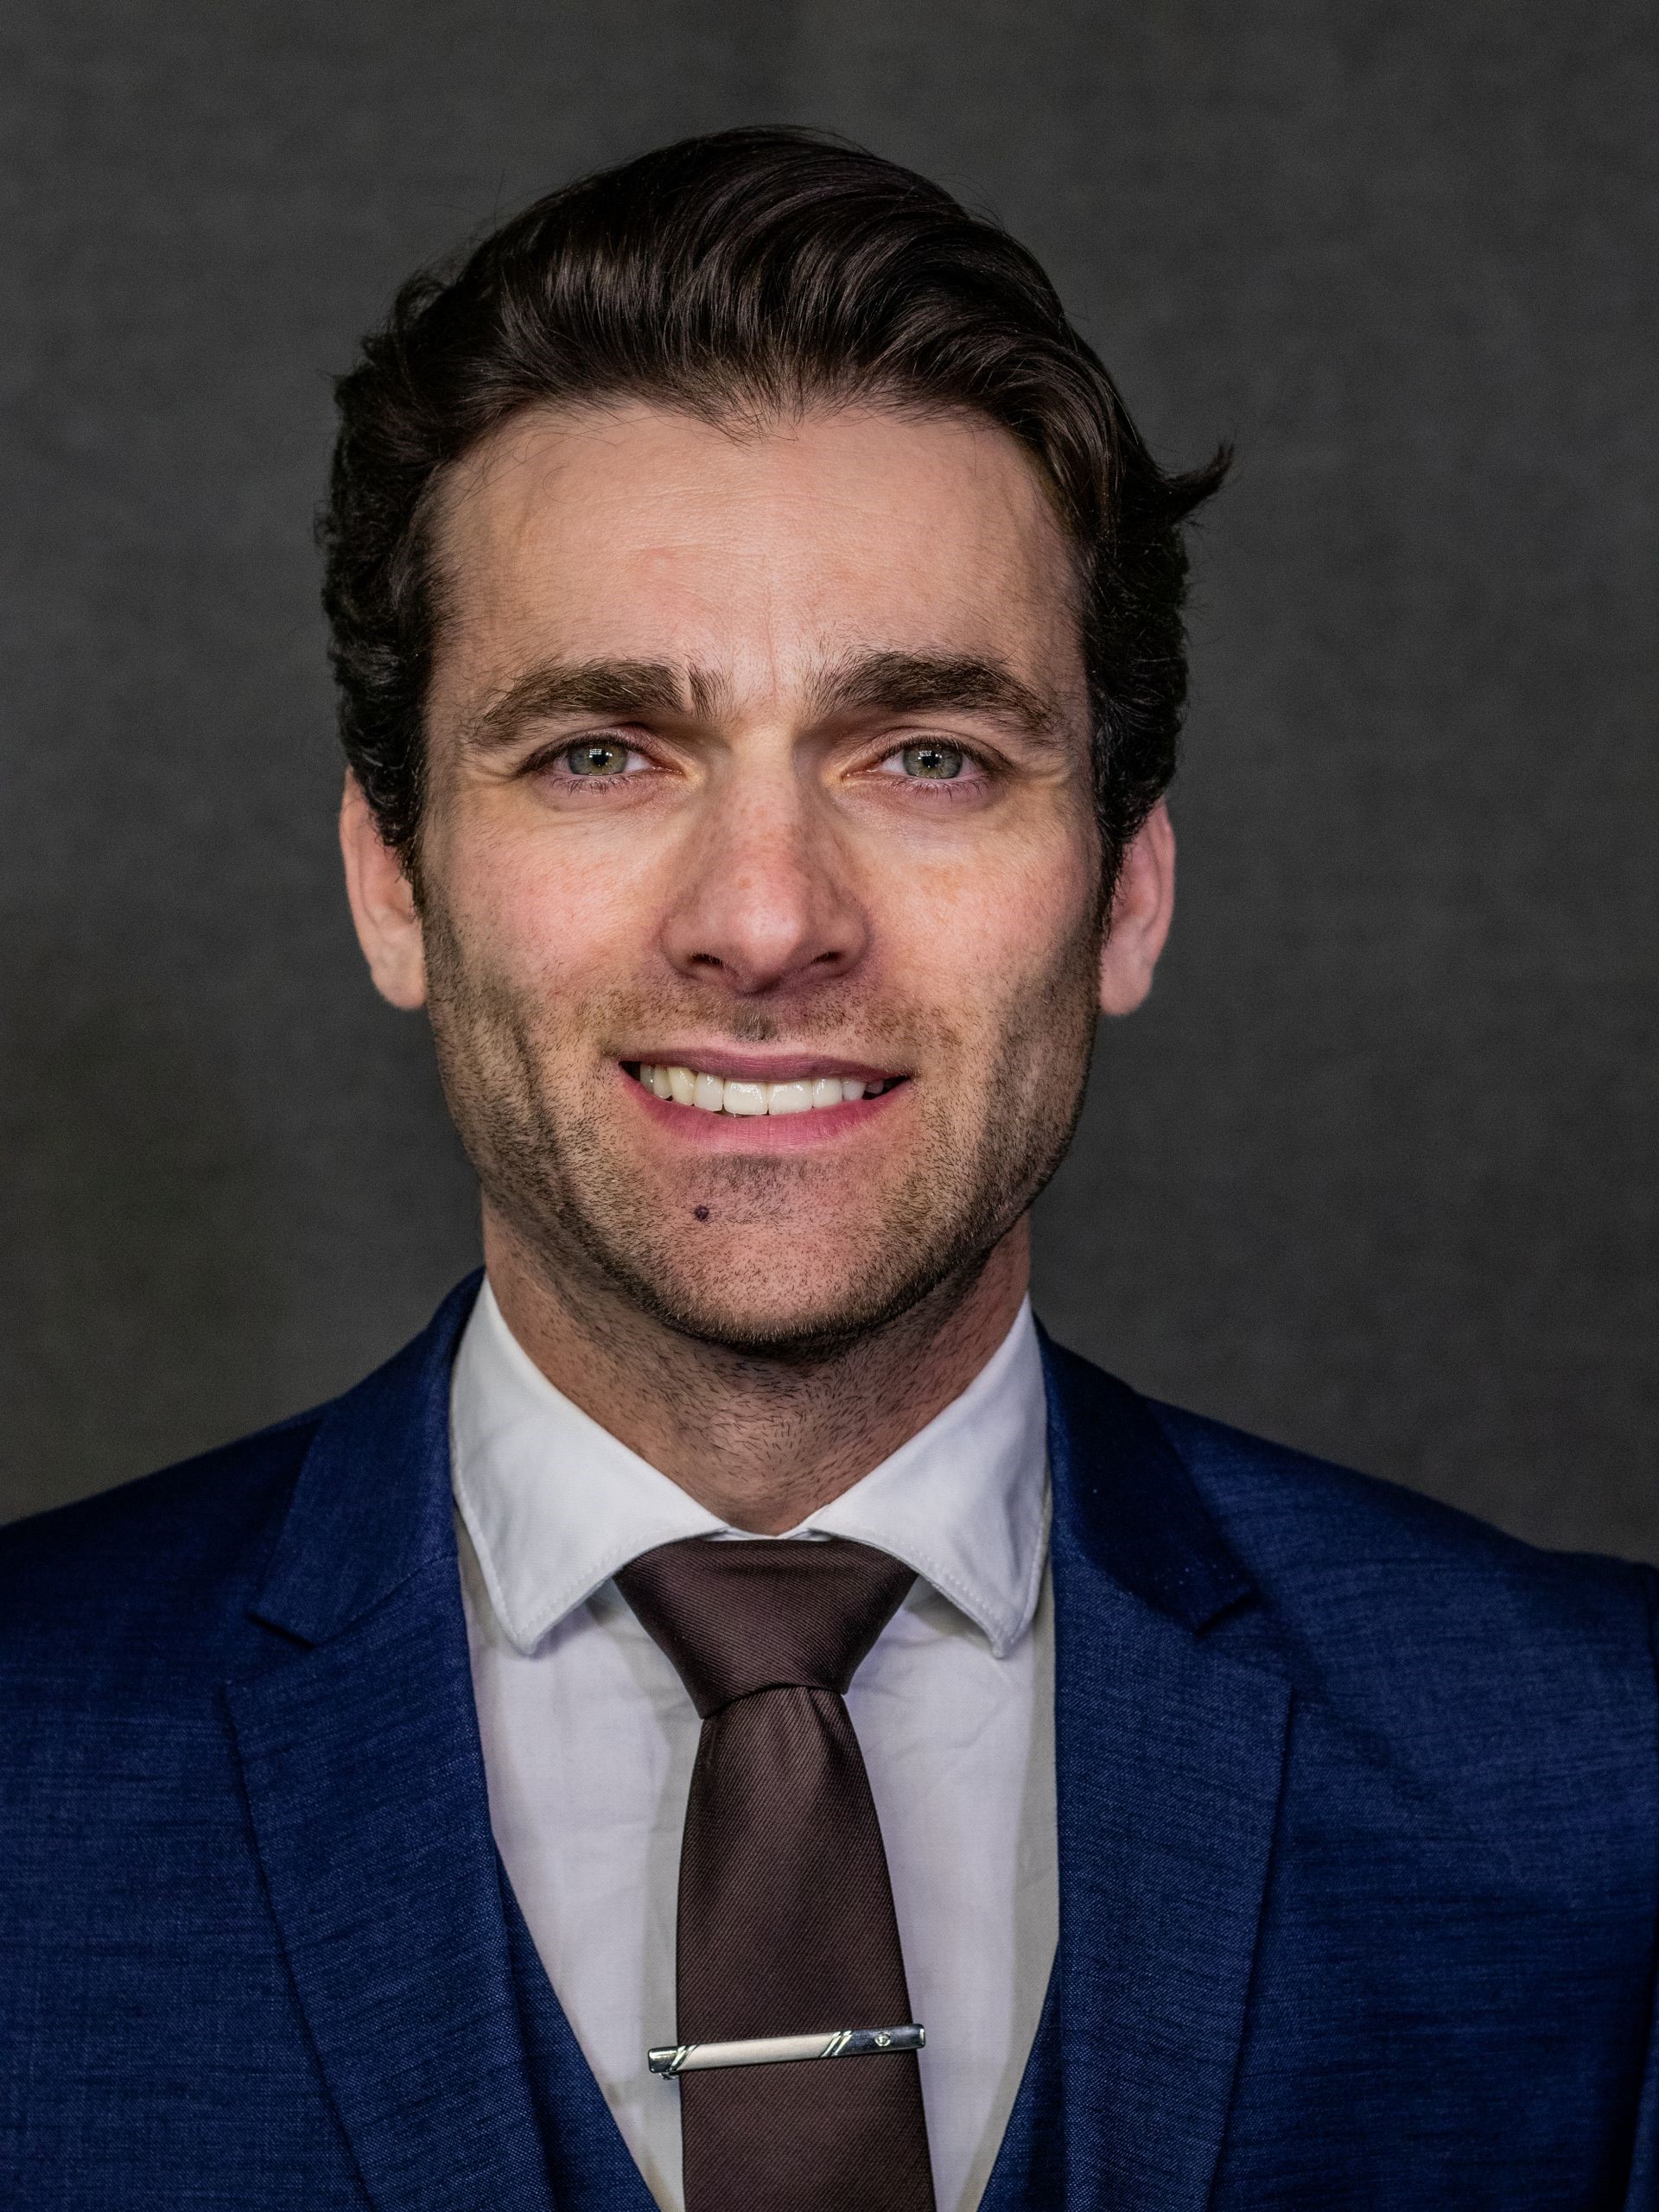
Marcus Oyelaran
Senior Loan Officer
Marcus runs our refinance desk and tracks rate sheets from every lender we work with, daily. If a 15-year fixed saves you real money, he will show you the math — and if refinancing does not pencil out, he will say so.
NMLS #2103948 · 12 years in mortgage lending
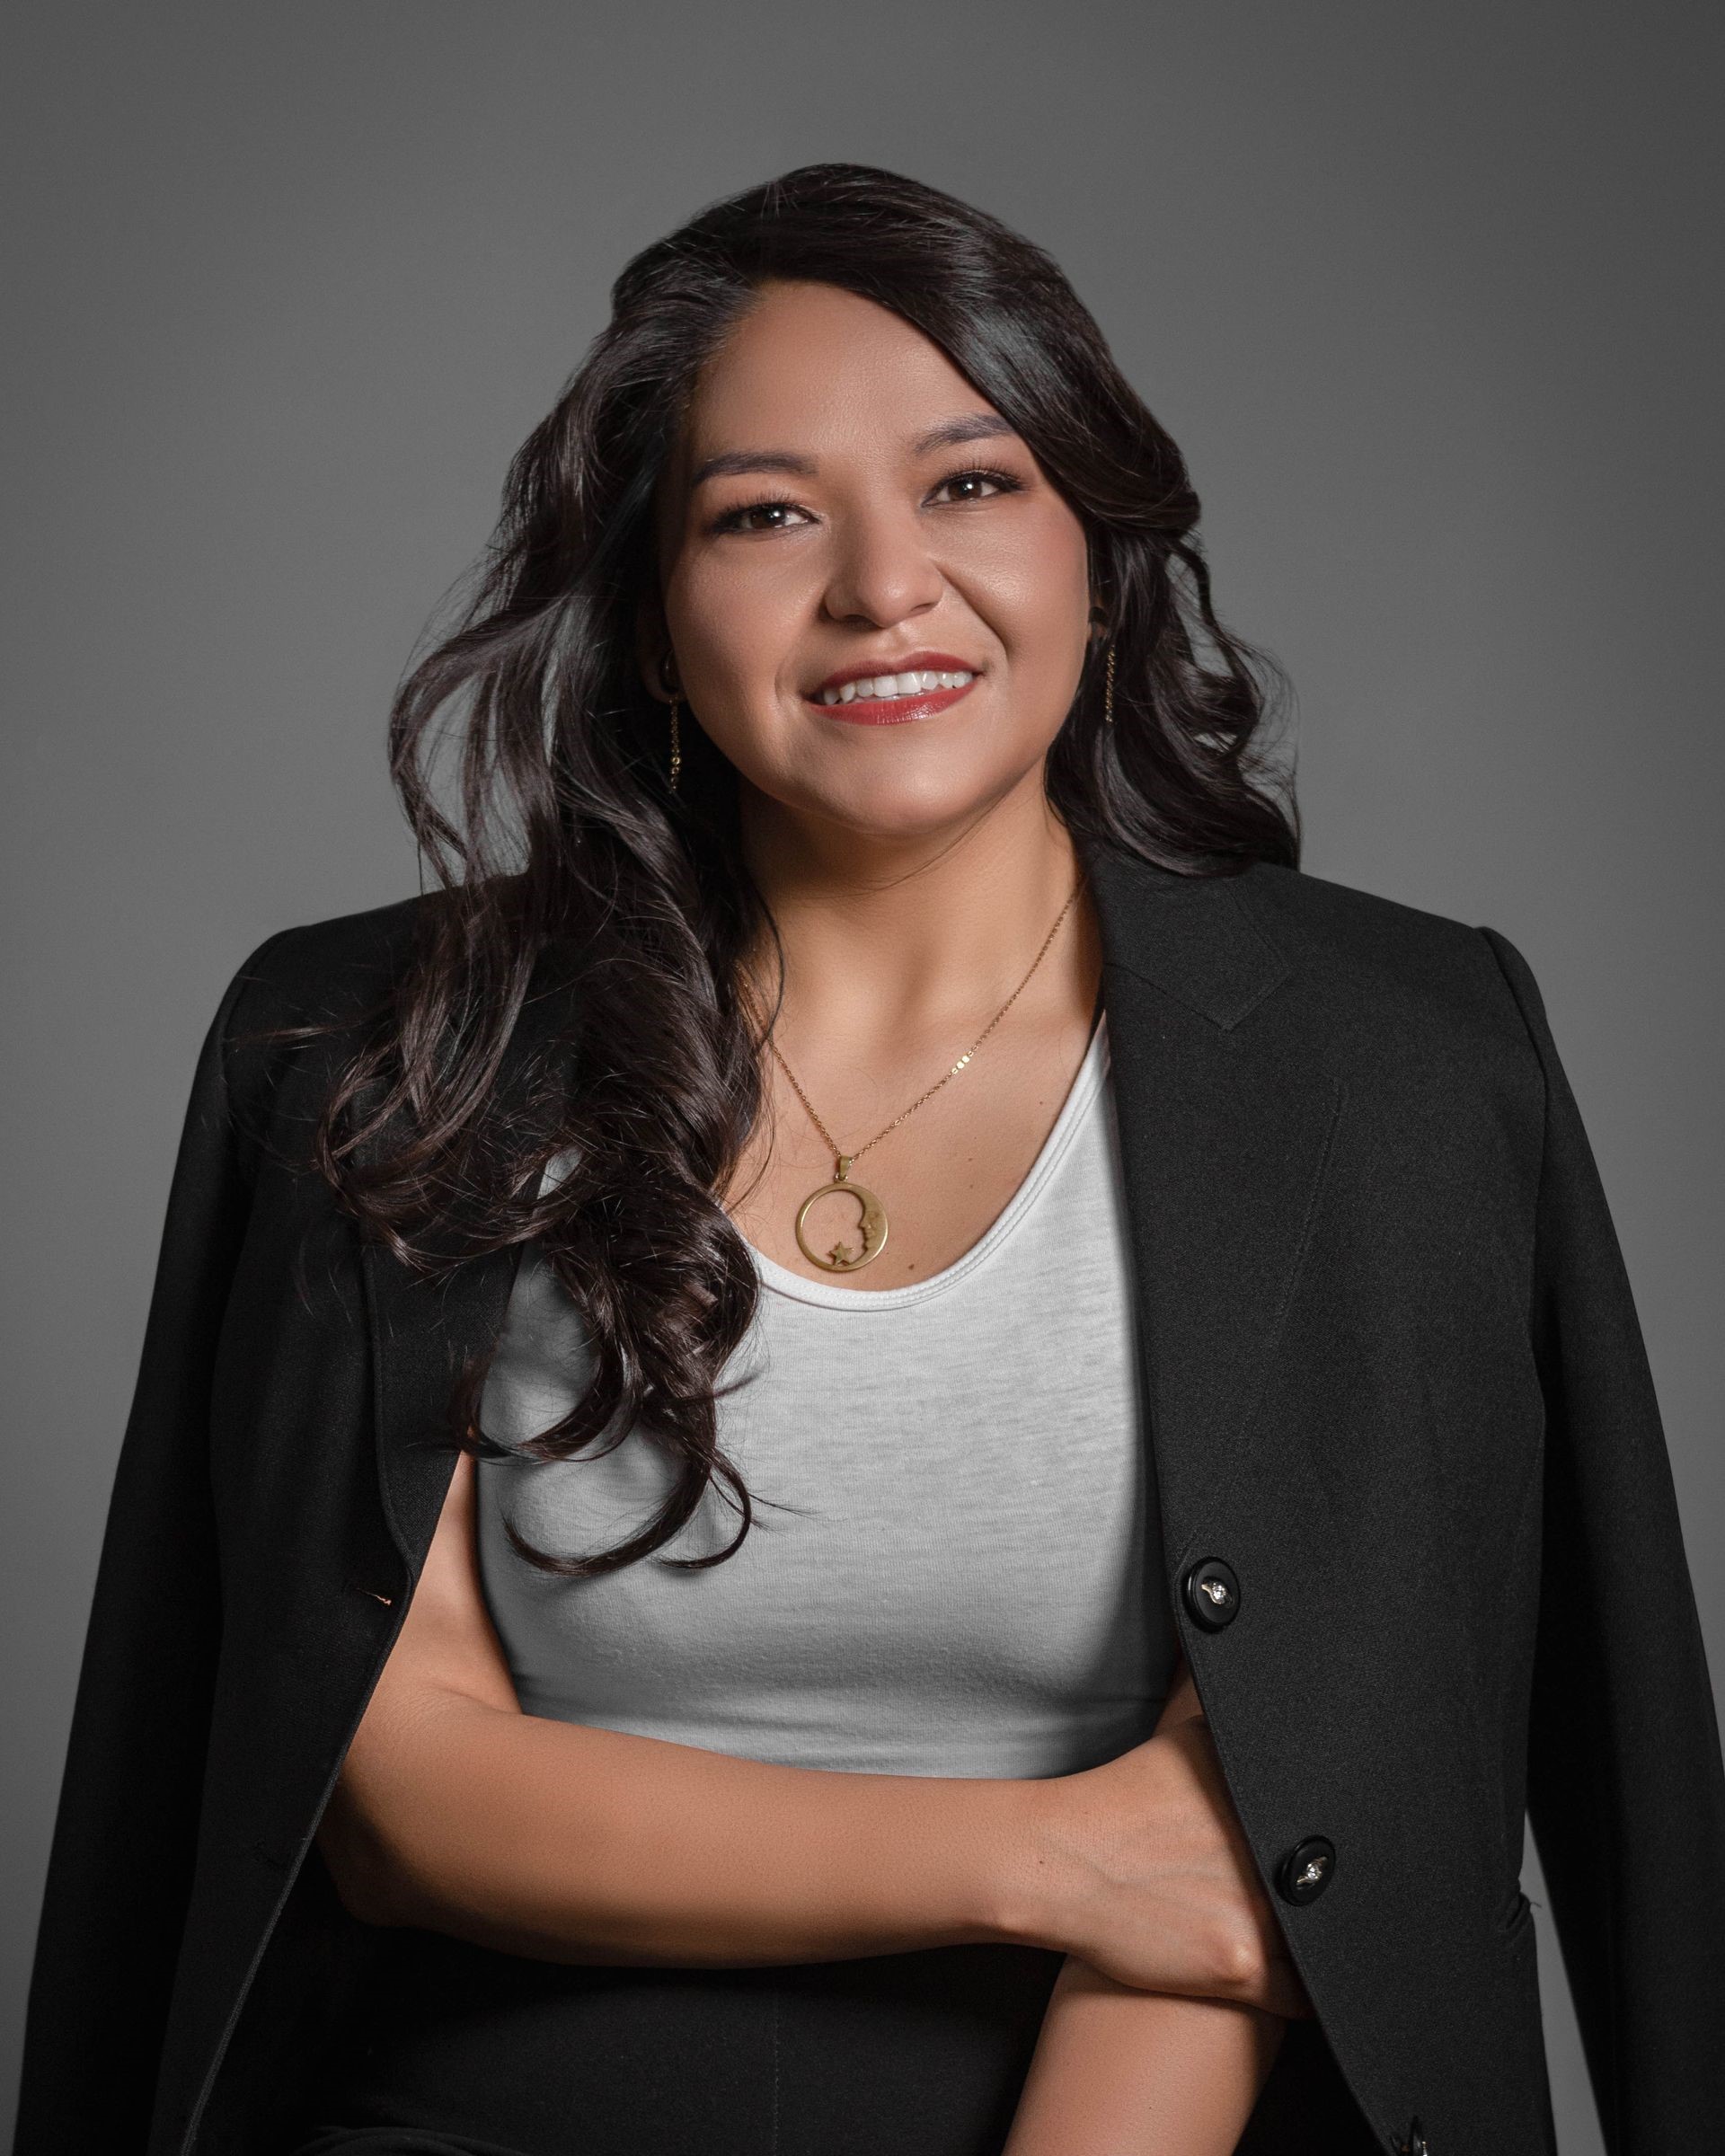
Priya Raman
Loan Officer, First-Time Buyer Programs
Priya guides first-time buyers through down payment assistance, FHA, and conventional 97 programs. She has closed over 300 purchase loans and answers every text herself.
NMLS #2394817 · 8 years in mortgage lending
FAQ
Straight answers for first-time buyers.
Will checking my rate hurt my credit score?
No. Pre-qualification uses a soft credit inquiry, which lets us give you a genuine rate estimate without affecting your score. A hard pull only happens later, if and when you formally apply for a specific loan.
What is the difference between pre-qualification and pre-approval?
Pre-qualification is a credible estimate of what you can borrow, based on a soft credit check and the information you give us — it takes about 10 minutes. Pre-approval means an underwriter has verified your income, assets, and credit, and a lender has committed in writing. In competitive markets, sellers expect a full pre-approval with your offer, and we will get you there quickly once you have a home in mind.
How much do I need for a down payment?
Less than most people think. Conventional loans start at 3% down for first-time buyers, FHA at 3.5%, and VA and USDA loans can go to 0% if you qualify. Putting 20% down avoids mortgage insurance, but it is not required — we will show you the trade-offs in dollars, not percentages.
What credit score do I need to buy a home?
Most of our lenders start at 620 for conventional loans and 580 for FHA. Better scores unlock better pricing — 740+ gets the best rates — but there are programs between those numbers too. If your score is below 620, talk to us before giving up; we have options, and we will tell you honestly what to fix first.
What are closing costs, and who pays them?
Closing costs typically run 2–5% of the loan amount and cover appraisal, title, insurance, recording fees, and prepaid taxes. They are negotiable — in many markets sellers contribute, and lenders can offer credits that roll costs into a slightly higher rate. We break down every line item before you commit.
Are broker rates actually better than going to a bank?
Often, yes — because we work with 40+ wholesale lenders whose pricing is not available on a bank branch wall, and a bank can only ever offer you its own products. We earn a flat fee paid at closing (disclosed up front, never hidden in your rate), so our incentive is to find the cheapest legitimate loan, not the one with the fattest margin.
How long does closing take?
Our median purchase close in 2026 was 28 days; refinances typically close in about 21. Delays usually come from documentation gaps, so we front-load underwriting — your file goes to a lender already knowing what the underwriter will ask for.
Question not covered here? Call (503) 555-0148 or send us your details — either way, you get a real answer.
Ready to see what you actually qualify for?
Ten minutes now, real numbers today. No hard credit pull, no obligation, no sales pitch.
Check my rate